
Categories
houston real estate, Military & Veteran Real Estate, VA LoanPublished October 4, 2026
Can You Use a VA Loan More Than Once? What Houston-Area Buyers Need to Know
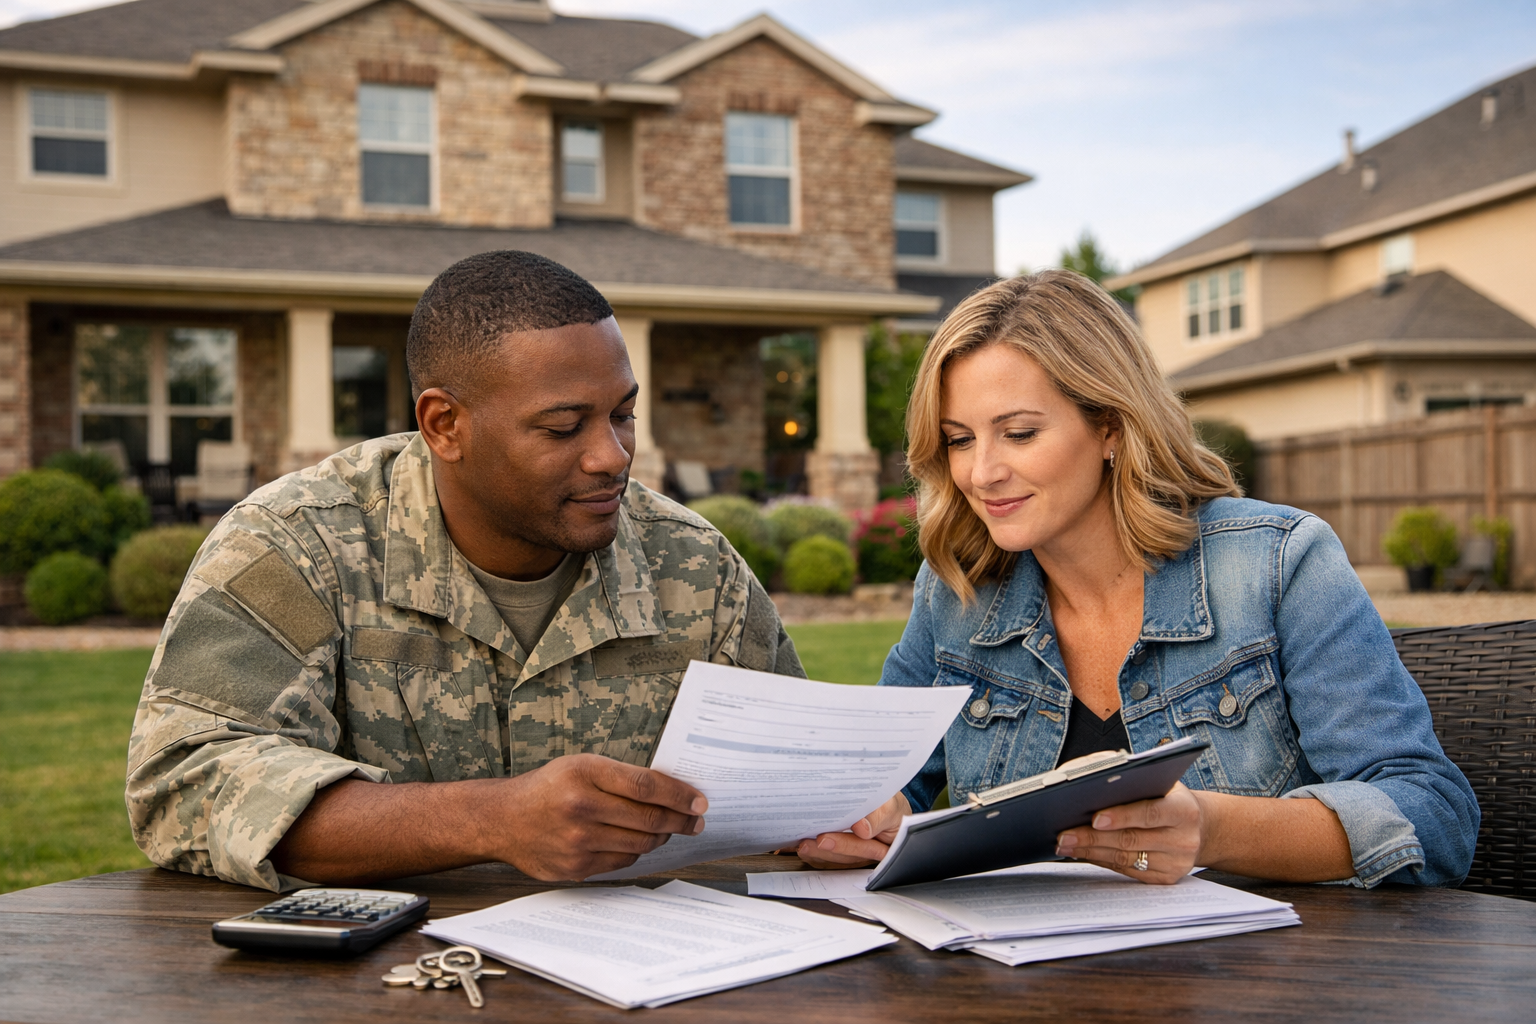
For many military service members and veterans, the VA home loan benefit can make homeownership more accessible. A common question for buyers in Houston and nearby communities such as Katy, Sugar Land, Pearland, The Woodlands, Cypress, and League City is whether a VA loan is a one-time benefit or something that can be used again later.
Yes, you can often use a VA loan more than once. In many cases, eligible buyers can reuse the benefit after selling a home and restoring entitlement, and some may be able to keep an existing VA-financed home and use remaining entitlement for another purchase. The exact path depends on entitlement, occupancy rules, lender requirements, and the details of the prior VA loan.
How VA Loan Reuse Works
A VA loan is not necessarily a one-and-done benefit. The program is designed so eligible borrowers may use it multiple times over the course of their lives, as long as they meet the VA's eligibility standards and have sufficient entitlement available for the new loan.
That matters for buyers whose housing needs change over time. A move across the Houston area, a permanent change of station, a growing household, or a relocation from one suburb to another can all raise the question of whether the VA benefit can be used again.
VA Loan Entitlement Basics
Entitlement is the portion of the loan the VA agrees to guarantee for an eligible borrower. In practical terms, entitlement helps reduce lender risk, which is why VA loans can offer favorable terms for qualified borrowers.
There are two key ideas to understand:
- Full entitlement: In some situations, an eligible borrower may have full entitlement available, which can provide more flexibility when purchasing with a VA loan.
- Remaining or partial entitlement: If part of your entitlement is tied up in an existing VA loan, you may still have some entitlement left to use for another home, depending on the circumstances.
Entitlement is not the same as automatic approval. Even if you are eligible for the VA benefit, a lender still evaluates income, credit, debt obligations, residual income, and other underwriting factors.
Can You Use a VA Loan More Than Once?
Yes. Many eligible borrowers use a VA loan more than once. The most common scenarios include:
- Buying a home with a VA loan, later selling it, and restoring entitlement for a future purchase
- Paying off a VA loan and applying for restoration of entitlement
- Keeping a current VA-financed home and using remaining entitlement to buy another primary residence
- Using a one-time restoration option in a qualifying situation
The right option depends on how your previous VA loan was handled and whether you still own the property.
Restoring Entitlement After Selling a VA-Financed Home
One of the most straightforward ways to reuse a VA loan is to sell the home that was financed with the VA loan and have the loan paid off at closing. Once the loan is satisfied, you can generally apply to restore your entitlement.
In many cases, this is the cleanest route for a buyer who is moving from one Houston-area home to another and wants to use the VA benefit again for a new primary residence.
Even when the prior home has been sold, restoration is not something to assume automatically without verification. It is important to confirm that the prior VA loan has been fully paid and that the restoration process has been completed properly.
Restoring Entitlement After Paying Off the Loan
You may also be able to restore entitlement after the VA loan has been paid in full, even if the path is different from a standard sale. For example, if the loan is fully satisfied and the property is no longer securing that VA-backed obligation, restoration may be available.
Because documentation and timing can matter, borrowers should confirm the restoration process directly with the VA and a VA-approved lender before assuming the benefit is fully available for a new purchase.
Keeping Your Current VA Loan and Using Remaining Entitlement
Some buyers do not want to sell their current home right away. This can happen when a homeowner converts a prior residence into a rental, relocates for work or military orders, or wants to buy in another part of the Houston area while keeping the first property.
In some cases, that borrower may still be able to use a VA loan again by relying on remaining entitlement. This is sometimes called using a second-tier or partial entitlement, although the exact terminology can vary.
Whether this works depends on several factors, including:
- How much entitlement is already tied to the existing VA loan
- The size of the new loan
- The county where the new property is located
- The lender's underwriting standards
- Whether the new home will meet VA occupancy requirements
This is one of the most misunderstood parts of the VA loan benefit. A borrower may be eligible to use the benefit again, but the amount available for the next purchase may be limited if part of the entitlement remains committed to the first home.
How County Loan Limits May Affect Partial Entitlement
When a borrower has full entitlement, county loan limits may not affect the same way they do in partial-entitlement situations. But when part of the entitlement is already in use, county loan limits can become relevant in determining how much additional VA-backed financing may be available without a down payment.
That does not mean every buyer with partial entitlement is blocked from purchasing. It means the structure of the next loan may be more complex. Depending on the loan amount and remaining entitlement, a borrower may need a down payment or may find that certain purchase scenarios work better than others.
Because county-based calculations can change and lender overlays differ, buyers should avoid relying on generic online examples and instead request a personalized entitlement review.
One-Time Restoration Scenarios
The VA may allow a one-time restoration of entitlement in certain situations when the original VA loan has been paid off but the property has not been sold. This can be valuable for borrowers who want to keep a home they previously financed with a VA loan and still use the benefit again.
However, this is not an unlimited option and should not be treated as a routine workaround. The rules, documentation requirements, and future implications should be reviewed carefully before moving forward. If you think this scenario may apply, confirm the details directly with the VA and your lender.
Occupancy Requirements and Common Exceptions
VA loans are intended for primary residences, not vacation homes or purely investment properties. In general, the borrower must intend to occupy the home as a primary residence within the required timeframe set by the lender and VA guidelines.
That said, there are situations where occupancy questions become more nuanced. Common examples include:
- PCS orders or military relocation: A service member may need to move due to orders after purchasing a home
- Spouse occupancy in some qualifying situations: Depending on the circumstances and lender guidance, occupancy by a spouse may satisfy requirements
- Deployment or other service-related timing issues: Certain exceptions or accommodations may apply based on military service circumstances
The key point is that occupancy is based on legitimate intent and program rules, not simply preference. If you plan to keep one home and buy another with a VA loan, occupancy is one of the first issues to review with your lender.
PCS and Relocation Considerations
Military moves do not always line up neatly with home sale timelines. A buyer leaving one area for Houston, or moving from Houston to another duty station, may need to decide whether to sell, rent out, or retain the current home before purchasing again.
In those cases, the VA loan conversation often includes:
- Whether the current VA loan will be paid off before the next purchase
- Whether enough entitlement remains for another VA-backed loan
- Whether the new purchase meets occupancy rules
- How the lender will evaluate the departing residence and any rental income
For relocating buyers, planning ahead matters. Reviewing entitlement and occupancy issues early can help avoid delays when it is time to make an offer on a home in Houston or the surrounding suburbs.
Common Mistakes Buyers Make
VA loan reuse can be highly beneficial, but several mistakes can create confusion or delays:
- Assuming the benefit is automatically restored: Restoration usually needs to be confirmed and documented
- Confusing eligibility with available entitlement: You may still be VA-eligible while having limited entitlement available for a new loan
- Ignoring occupancy rules: A VA loan is generally for a primary residence, not a second home or investment purchase
- Overlooking lender overlays: A lender may have stricter requirements than the baseline VA guidelines
- Waiting too long to review entitlement: This can become a problem when you are already under contract
- Relying on outdated examples: Loan calculations and interpretations can vary based on current guidance and lender policies
Practical Next-Steps Checklist
- Request your Certificate of Eligibility and entitlement review. Confirm whether you have full, restored, or remaining entitlement.
- Identify the status of any current or prior VA loan. Determine whether the loan has been paid off, whether the home has been sold, and whether restoration has been completed.
- Discuss occupancy plans clearly. Explain whether you will live in the new home as your primary residence and whether relocation or military orders affect timing.
- Ask about partial entitlement scenarios. If you are keeping a current home, have a VA-approved lender review how much entitlement may remain for another purchase.
- Review lender-specific requirements. Credit, debt-to-income, residual income, reserves, and documentation standards can vary.
- Coordinate early if you are relocating. If you are moving to or within the Houston area, line up your financing review before home shopping gets serious.
- Verify all assumptions before making an offer. Confirm eligibility, entitlement, occupancy, and loan structure with the VA and your lender.
FAQ: Using a VA Loan More Than Once
Can I have two VA loans at the same time?
Sometimes, yes. If you have remaining entitlement and meet occupancy and lender requirements, you may be able to keep one VA-financed home and use a VA loan again for another primary residence.
Do I have to sell my current home to use a VA loan again?
No. Selling is one common path, but some borrowers may qualify to use remaining entitlement or a one-time restoration option, depending on the situation.
Is entitlement automatically restored after I pay off my VA loan?
Not always in a way you should assume without verification. Restoration should be confirmed through the proper process with the VA and your lender.
Can I use a VA loan for an investment property?
Generally, no. VA loans are intended for primary residences, although a home you once occupied may later become a rental after a legitimate change in circumstances.
What if I am moving because of PCS orders?
PCS orders can affect occupancy and timing considerations. They may also support a legitimate reason for keeping one home while purchasing another primary residence elsewhere.
Will county loan limits matter for my next VA loan?
They may matter if you have partial entitlement. When part of your entitlement is already in use, county-based calculations can affect how much additional VA-backed financing may be available.
Final Takeaway
For many eligible military and veteran buyers, a VA loan can be used more than once. The main questions are not simply whether reuse is allowed, but how much entitlement is available, whether restoration is needed, whether occupancy rules are satisfied, and how the lender will structure the next loan.
If you are planning a move within Houston or to a nearby suburb, it is wise to review your entitlement status before you start the buying process. A clear understanding of your options can help you move forward with fewer surprises.
Important note: VA loan rules can depend on your specific circumstances. Eligibility, entitlement, occupancy, and lender requirements should be confirmed directly with the U.S. Department of Veterans Affairs and a VA-approved lender before making financing decisions.
Get a free home valuation here
Visit our website here
Go to our YouTube Channel Here
Call or Contact us:
832-905-9501
mflores@vantagerec.com
Vantage Real Estate Group Powered by PLACE
Michael Flores
Owner/Lead Agent | Vantage Real Estate Group | Keller Williams Signature Realty
or another way