
Categories
2026 real estate forecast - Houston Metro Area, Fulshear, hispanic homebuyers, Home Buying Process, Home Buying Strategies, Housing Market, houston real estate, katy isd schools, katy schools, lamar cisd schools, Luxury, Military & Veteran Real Estate, Neighborhood Spotlights, New Construction, New Buyers, Purchasing Real Estate, Seller Tips, West Houston Real EstatePublished November 16, 2026
The Hidden Cost of Buying a Home in Fulshear, Texas: What Builders Aren't Telling You in 2026
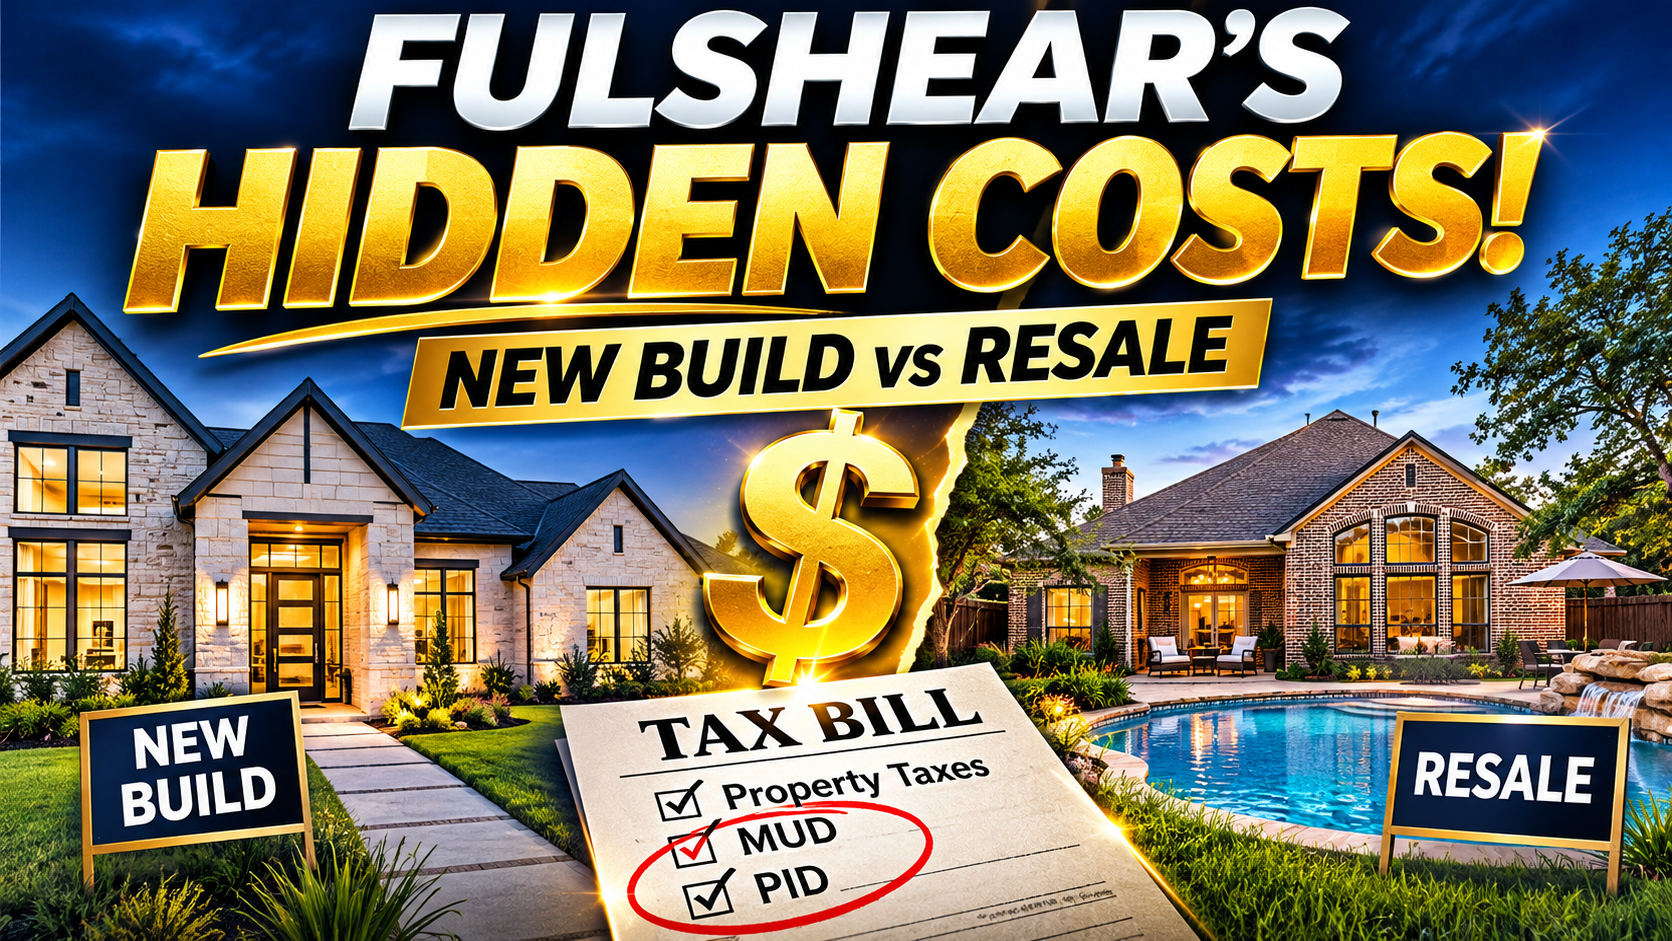
The Hidden Cost of Buying a Home in Fulshear, Texas: What Builders Aren't Telling You in 2026
Imagine walking into a beautiful model home in Fulshear, Texas.
The floors are spotless. The kitchen looks like something out of a luxury magazine. The backyard is full of possibilities, and the sales representative has just delivered the words every homebuyer loves to hear.
"We can get you a mortgage rate under 5%."
Your eyes light up.
After months of watching mortgage rates and wondering whether buying a home is even affordable anymore, you've just found what feels like the deal of a lifetime.
But just a few miles away, another home is sitting on the market.
It's slightly older. The landscaping is mature. The backyard already has a swimming pool. The owners have installed the blinds, upgraded the patio, purchased the appliances, and taken care of many of the little expenses nobody thinks about when buying a brand-new home.
And here's where things get interesting.
The house with the lower mortgage rate isn't necessarily the house that will cost you less to own.
Welcome to the Fulshear real estate market in 2026, where the price on the sign is only the beginning of the story.
And depending on how well you understand the numbers, that story could save you—or cost you—tens of thousands of dollars.
Fulshear Isn't the Small Texas Town It Used to Be
There was a time when Fulshear was little more than a quiet crossroads west of Houston.
In 2000, the community had fewer than 1,000 residents. People came here for the open land, the peaceful surroundings, and the opportunity to escape the congestion of the city.
Then something extraordinary happened.
Houston kept growing west, and Fulshear became one of the region's most desirable places to build a home.
What was once ranchland became master-planned communities. Country roads began leading to expansive neighborhoods, beautiful amenity centers, parks, lakes, and thousands of newly constructed homes.
Communities such as Cross Creek Ranch, Jordan Ranch, Cross Creek West, Fulshear Lakes, and Tamarron changed the landscape.
Families weren't simply buying houses. They were buying a lifestyle.But rapid growth comes with consequences, especially when developers, homebuilders, and local infrastructure systems are all expanding at the same time. For years, buyers felt they had to make decisions quickly. Homes sold fast, prices climbed, and negotiations often favored the seller.
Now the market is changing.
By late 2026, Fulshear's housing supply has expanded, and buyers have more opportunities to compare properties, negotiate terms, and question the numbers. That shift is important. Because when buyers have choices, they can stop asking, "How fast do I need to buy this house?" And start asking a much better question.
"Is this actually the best financial decision for my family?"
That one question changes everything.
The Builder's Secret Weapon: A Mortgage Rate That Looks Almost Too Good to Be True
Picture two homes.
One is a brand-new $500,000 home in a beautiful master-planned community. The other is an established resale home listed for $480,000 just a few miles away. The new home comes with an advertised mortgage rate of 4.99%. The resale home is being financed at 7.25%.
At first glance, the decision seems obvious.
Why would anyone pay a higher interest rate for an older home when a builder is offering something significantly better?
The answer starts with understanding how large homebuilders operate. National and regional builders have something individual homeowners generally don't: massive financial resources and relationships with mortgage companies. Builders can arrange subsidized mortgage financing, including through bulk mortgage commitments, that allows qualifying buyers to obtain rates below ordinary market offerings. They may also offer closing-cost credits, design upgrades, or other incentives.
During promotional periods, some Fulshear-area builders have advertised tens of thousands of dollars in financing assistance and upgrades.
For a buyer, these incentives can be extremely valuable. And make no mistake, a genuinely favorable mortgage rate can save a family a considerable amount of money over time.
But there's another side to the story.
Builder incentives often come with conditions. The buyer may need to use a preferred lender, meet a contract deadline, close on a specific property, or satisfy particular financing requirements. And sometimes the most attractive advertised rate is available only on certain homes or loan programs. A promotional rate also doesn't automatically mean the property itself is priced competitively.
That's why you never want to shop for a home based on the mortgage rate alone.
You want to understand the complete financial picture.
A $20,000 Cheaper Home Can Have a Higher Mortgage Payment
Let's return to those two houses.
The brand-new home costs $500,000. With a 10% down payment, the buyer finances $450,000 at 4.99%.
The monthly principal and interest payment is approximately $2,414. The resale home costs $480,000. With the same 10% down payment, the buyer finances $432,000 at 7.25%. That monthly principal and interest payment is approximately $2,947.
Think about that. The resale home costs $20,000 less to purchase, yet its monthly mortgage principal and interest payment is approximately $533 higher.
That's almost $6,400 a year.
Suddenly, the brand-new house looks like the obvious winner.
And if we stopped the conversation right here, you might be correct. But we haven't discussed property taxes.
And in Fulshear, that's where the story can take a dramatic turn.
The Tax Bill That Can Change Everything
One of the biggest surprises facing buyers in Fulshear is that two houses with similar purchase prices can carry dramatically different property tax bills.
You could buy a $500,000 home in one neighborhood and pay thousands of dollars more in annual property taxes than someone living in a similarly priced home a few miles away.
Why?
Because not every Fulshear neighborhood has the same taxing authorities. Texas property taxes are made up of several separate pieces. Depending on the property's exact location, you may be paying taxes to Fort Bend County, a school district, an emergency services district, the City of Fulshear, and a Municipal Utility District.
It's that last one—the MUD—that deserves special attention.
A Municipal Utility District helps finance the infrastructure needed to turn undeveloped land into residential communities.
We're talking about water systems, wastewater facilities, drainage, and other essential infrastructure. All those beautiful new neighborhoods require enormous investments before the first homeowner ever moves in. And somebody has to pay for those investments.
Often, that somebody is the homeowner, through property taxes that help repay the district's outstanding debt.
In newer neighborhoods, those MUD-related tax rates can be substantial. In older communities, where infrastructure debt has been reduced or retired, the tax burden may be significantly lower. That difference can have a major impact on affordability.
What does that actually look like on a $500,000 house?
Consider two hypothetical homes with the same $500,000 taxable value.
One is located in a newer community with a combined property tax rate of approximately 2.885%. The other is in an established neighborhood with a combined rate of approximately 2.036%.
The newer home's annual property tax bill would be roughly $14,425. The established home's bill would be approximately $10,180.
That's a difference of more than $4,200 every year. Or about $354 every month.
And now, that mortgage-rate advantage we were celebrating earlier doesn't look quite as dramatic.
Remember the approximately $533 monthly principal and interest savings on the new home? A $354 monthly difference in property taxes would consume a large portion of it. The remaining advantage would be approximately $179 per month, before considering insurance, HOA dues, maintenance, or additional improvements. These are illustrative calculations, not actual tax estimates for either property. Real bills depend on the exact parcel, applicable districts, taxable value, and exemptions.
But the lesson is clear.
A low interest rate can save you money. A higher property tax bill can quietly take a large portion of that savings right back.
This is why I tell people that the most important number in real estate isn't always the purchase price.
It's the total cost of owning the home.
Your Fulshear Address Doesn't Tell the Whole Story
There's another detail buyers need to understand.
Just because a house has a Fulshear mailing address doesn't automatically mean it's inside the incorporated City of Fulshear.
Some properties are within city limits. Others are outside those boundaries. That matters because city property taxes generally apply only to properties within the city.
School district boundaries create another layer of complexity.
Depending on the exact location, a Fulshear-area home may fall within Lamar Consolidated ISD or Katy ISD. And school taxes are often one of the largest portions of the total property tax bill. The school assignment also matters tremendously to families who are making housing decisions based on education.
Two homes within the same general community may not necessarily have the same school assignments or tax jurisdictions.
Never assume that a ZIP code, neighborhood entrance sign, or model-home brochure tells the entire story.
Before buying, verify the individual property's tax account and school boundaries.
A few minutes of research can prevent years of expensive surprises.
The Contract Nobody Wants to Read Until Something Goes Wrong
There's something exciting about buying a brand-new home.
You may get to choose your flooring, cabinets, countertops, and finishes. Everything feels personal. But signing a contract with a production builder isn't necessarily the same experience as purchasing an established resale home. Many builders use their own proprietary purchase agreements. These contracts can contain provisions dealing with deposits, construction delays, financing, changes to the property, inspections, and cancellation rights. And those provisions deserve your attention long before you start picking out backsplash tile.
Here's a situation worth imagining.
You sign a contract on a home that won't be completed for several months. You put down earnest money. You select upgrades. You begin planning your move. Then something unexpected happens. Your financing changes. Construction takes longer than expected. Your circumstances shift. Or the completed home doesn't meet your expectations.
What happens to your deposit?
Can you cancel?
Does the builder have the right to extend construction?
What remedies do you have?
The answers depend on the actual agreement you signed. That's why buyers should review their builder contracts carefully and understand the consequences before committing.
And one more thing.
The friendly representative sitting inside the model home is there to sell the builder's homes. That doesn't make the representative dishonest or unhelpful. It simply means the builder's interests and your interests aren't necessarily identical.
Having independent representation can make an enormous difference when evaluating contract terms, incentives, property taxes, inspections, and the overall purchase.
A Brand-New Home Can Still Have Problems
One of the biggest misconceptions about new construction is that a brand-new home doesn't need an inspection.
After all, nobody has ever lived there.
Everything is new.
What could possibly be wrong?
Quite a bit, actually.
New homes are built by people. Different subcontractors handle different parts of the project, and mistakes can happen.
That's why independent inspections are so important. Ideally, inspections should happen at several points throughout construction. Before the foundation is poured, an inspector can review accessible foundation preparation and reinforcement details. Before drywall goes up, an inspector can evaluate visible framing, electrical wiring, plumbing, and HVAC components. And before closing, a final inspection can identify issues with the finished home. It's also worth considering an inspection near the end of the builder's initial workmanship warranty period.
The goal isn't to assume something is wrong.
It's to find problems while they can still be addressed efficiently.
Because discovering an issue before the walls are closed is usually a much better situation than discovering it after your furniture has arrived.
The $30,000 Surprise Waiting After Closing
Let's talk about one of the most overlooked expenses of buying a newly constructed home.
The house is finished.
You've signed the paperwork.
You have the keys.
You're officially a homeowner.
Then you walk inside and realize you still have a long list of things to purchase.
The windows need blinds.
The refrigerator isn't included.
You need a washer and dryer.
The backyard is mostly unfinished.
You want additional ceiling fans.
The garage needs improvements.
And that beautiful outdoor living space you imagined during the model-home tour?
You may have to pay for much of it yourself.
Depending on the home and what's included in the builder's contract, buyers can spend an additional $15,000 to $30,000 or more making a new house feel complete. Think about what that means. You've just made a down payment, paid closing expenses, and moved your family. Now you're spending thousands of additional dollars on improvements that may already exist in a competing resale home. This is where older homes can suddenly become very attractive.
An established resale might already have custom window treatments, mature landscaping, an irrigation system, upgraded appliances, a covered patio, and a finished backyard.
And many of those improvements are effectively included in the price you negotiate.
Instead of paying cash for everything after closing, you're acquiring a home where someone else has already invested the money, time, and effort. That's a significant difference. Especially for families who want to move in and start living rather than begin another round of projects.
The Swimming Pool Story Every Fulshear Buyer Should Hear
Now let's talk about the backyard.
Because in Southeast Texas, a swimming pool can be a very appealing feature.
Imagine a hot July afternoon. The kids are swimming. Friends are coming over. Someone is cooking outside. You don't have to pack up the car or head to a community pool. It's all right there. For many families, that's part of the dream.
But building a pool can be expensive.
A custom in-ground pool in the Fulshear area can easily cost $70,000 to $120,000 or more, depending on its design, features, and construction requirements. Now here's the part that surprises many homeowners. Spending $100,000 on a pool doesn't mean your home automatically becomes worth $100,000 more.
Real estate markets don't work that way.
A pool's resale contribution depends on comparable sales, buyer demand, lot configuration, condition, and the neighborhood.
Sometimes the market recognizes only a fraction of the original installation cost. That's disappointing news for the owner who paid to build it. But it can be very good news for the buyer purchasing that property years later.
Imagine finding a resale home with a beautiful pool, finished landscaping, outdoor kitchen, and covered patio.
The previous owner may have spent well over $100,000 improving the backyard. Yet the home's asking price may reflect only part of that investment. Suddenly, you're looking at a lifestyle that would cost considerably more to recreate from scratch.
Of course, a pool also creates ongoing expenses.
Chemicals, electricity, cleaning, equipment repairs, insurance considerations, and eventual resurfacing all need to be considered.
Not everyone wants that responsibility. And in communities with resort-style pools, splash pads, and water parks, some families are perfectly happy enjoying the amenities without maintaining a private pool.
But if a backyard pool is part of your dream, an established resale home deserves serious consideration before you decide to build one yourself.
Why Resale Sellers Can't Ignore the Builders
Now let's turn the conversation around.
What if you're not buying a home in Fulshear?
What if you're trying to sell one?
You might have a beautiful property with upgrades, a finished backyard, and years of careful maintenance.
And yet buyers keep visiting new-construction communities.
Why?
Because a builder may be offering a mortgage rate or financing package you can't easily match. For homeowners trying to sell, this is one of the most important realities of the 2026 Fulshear market. You're not competing only against your neighbor's house. You're also competing against professionally marketed builder inventory, model homes, mortgage incentives, and large companies with substantial advertising budgets.
That doesn't mean you have to give your home away.
It means you need to understand what buyers are comparing. Sometimes a price adjustment makes sense. Other times, a properly structured seller concession may have a greater effect on the buyer's affordability. A seller might contribute toward eligible closing costs or help fund a temporary mortgage rate buydown, subject to the buyer's loan guidelines.And there's another opportunity that too many sellers overlook.
Sell the value of what's already finished.
Don't simply say the house has a backyard. Explain that it has mature landscaping, an extended patio, irrigation, and fencing.
Don't just say the home has upgraded windows. Show the value of the custom shutters or blinds. Don't list appliances as an afterthought.
Make buyers understand how much money and effort they may avoid spending after closing.
A resale home has something a newly built house doesn't necessarily offer.
Someone else has already handled years of improvements. That's a compelling story when it's presented correctly.
The Biggest Mistake Buyers Make in Fulshear
After looking at all these numbers, incentives, and trade-offs, you might be wondering whether new construction is worth it.
Absolutely.
For the right buyer, a brand-new home can be a fantastic decision. You may get a modern floor plan, better energy efficiency, current building standards, warranty coverage, and attractive financing opportunities. You may also get exactly the layout and features you want. But established resale homes have meaningful advantages too.
They may offer larger lots, mature trees, finished yards, existing pools, additional upgrades, and potentially lower property tax rates.
The mistake isn't choosing new construction.
And it isn't choosing resale.
The mistake is making the decision before you've compared the true cost of both options.
When I evaluate homes, I want to know more than what the seller or builder is asking.
I want to understand what the monthly mortgage payment will be.
I want to see the exact property tax jurisdictions and applicable MUD obligations.
I want to understand homeowners insurance, HOA dues, and any additional fees.
I want to know how much cash the buyer will need immediately after moving in.
And I want to know whether the property makes sense for the buyer's long-term goals. Because the right home isn't simply the one with the prettiest kitchen or the lowest advertised interest rate. It's the home that fits your life and supports the future you're trying to build.
The Opportunity Nobody Should Overlook in 2026
Here's what I find exciting about today's Fulshear housing market.
Buyers have choices.
That's something we couldn't always say during the intense seller's market of a few years ago.
Instead of feeling forced to make an immediate offer, buyers can examine different neighborhoods, compare builders, evaluate resale properties, and negotiate from a more informed position.
And sellers who understand today's competition can position their homes more intelligently. A beautifully maintained resale home with valuable upgrades can be a serious competitor to a builder's inventory. A newly constructed home with a genuine financing advantage can also represent excellent value. The opportunity isn't exclusively on one side of the market.
It's in understanding the difference.
The best real estate decisions are rarely made by looking at one number.
They're made by connecting all the numbers to the life you want to live.
Before You Buy a Home in Fulshear, Ask Yourself This
When you're standing inside a gorgeous model home, it's easy to picture your family celebrating holidays, entertaining friends, and making memories.
That's exactly what a home should be about.
But before you fall in love with the countertops or start imagining furniture arrangements, ask a few important questions.
What will this home really cost every month?
How much will I pay in property taxes?
What improvements will I need to make after closing?
How does this compare with an established home nearby?
And most importantly, am I buying the right home—or simply responding to the most attractive advertisement?
The difference matters. Because a home should be a place where you build memories, financial stability, and a better future.
Not a place where unexpected expenses quietly drain your bank account.
The Bottom Line: Don't Just Buy the House. Understand the Deal.
Fulshear is one of the most exciting communities in the Houston area.
Its growth, neighborhoods, schools, lifestyle amenities, and housing opportunities have attracted families from across the region.
But buying a home here requires more than choosing between a new house and an older one.
It requires understanding how mortgage rates, builder incentives, property taxes, MUD districts, closing expenses, and existing improvements all fit together.
A builder's promotional mortgage rate might be an exceptional opportunity.
An established resale home might offer greater long-term value.
The winner is the property that makes the most sense once you understand the complete picture.
And that's what Houston Untold is all about.
Going beyond the beautiful photos, flashy incentives, and marketing headlines to reveal the details that actually matter.
Because sometimes the most expensive mistake in real estate isn't paying too much for a house.
It's failing to understand what you're really buying.
Thinking about buying or selling in Fulshear, Texas?
Before you make your next move, let's compare the options, examine the numbers, and make sure you're walking into the right opportunity.
A great home should help you build your future—not leave you wondering where all your money went.
Houston Untold — The stories behind the neighborhoods, the numbers, and the decisions that shape life in Greater Houston.
Get a free home valuation here
Visit our website here
Go to our YouTube Channel HereCall or Contact us:
832-905-9501
mflores@vantagerec.com
Vantage Real Estate Group Powered by PLACE
Michael Flores
Owner/Lead Agent | Vantage Real Estate Group | Keller Williams Signature Realty
or another way