
Categories
VA Loan, houston real estate, Katy TX, Military & Veteran Real EstatePublished October 19, 2026
The Biggest VA Loan Mistakes Houston Buyers Can Avoid
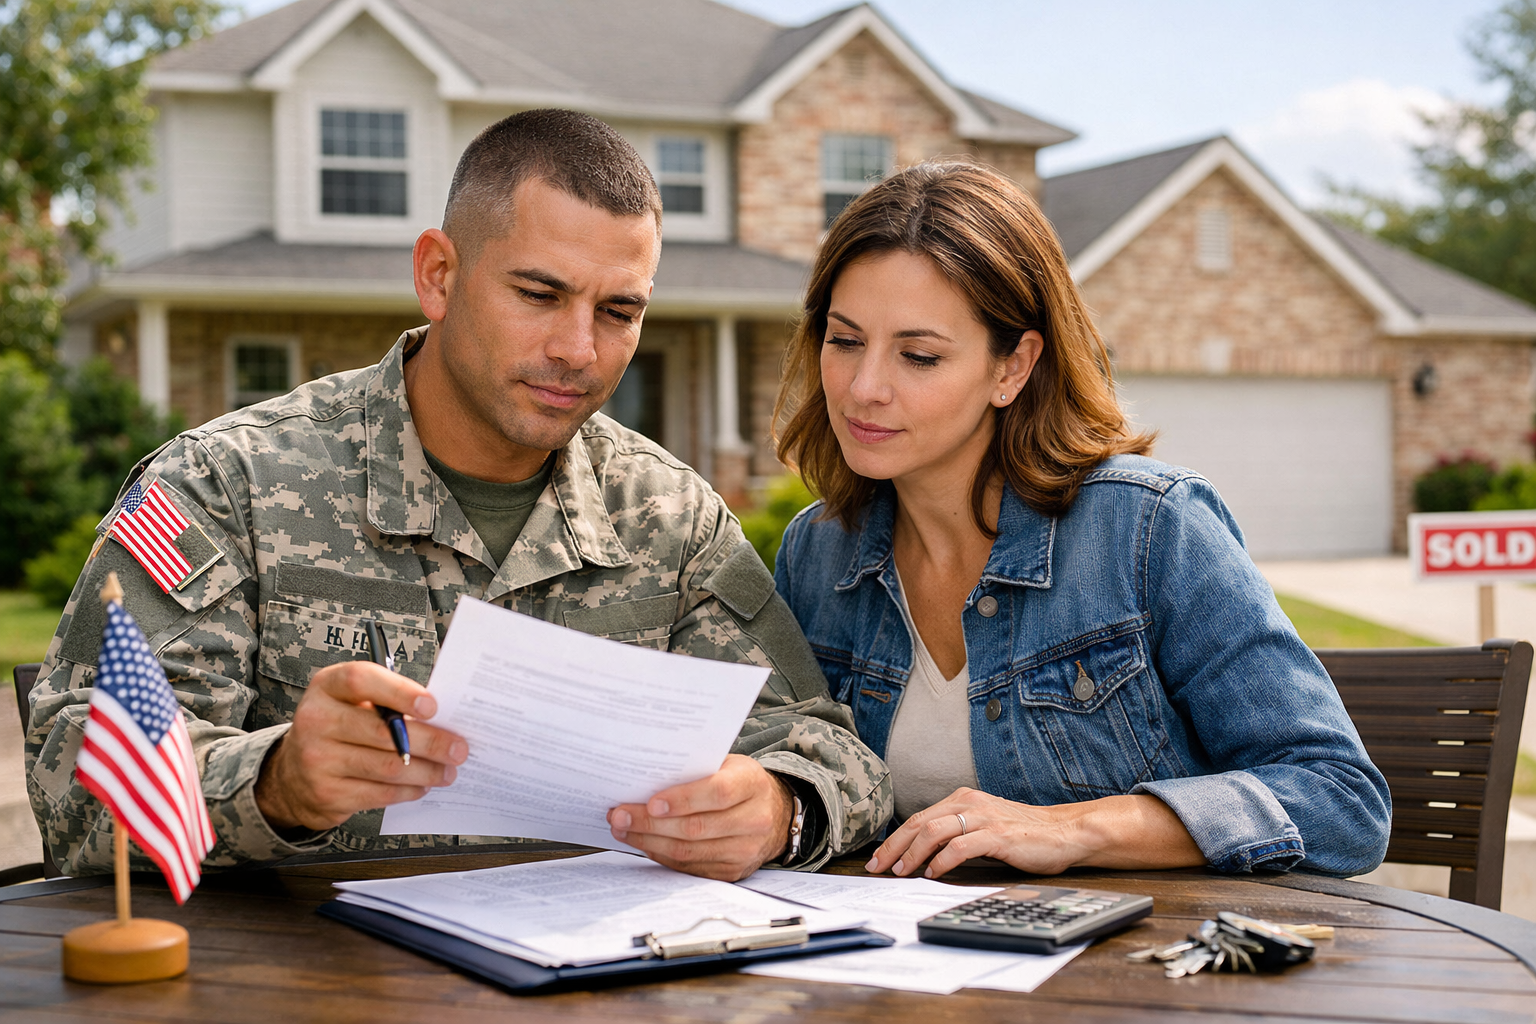
“These VA loan mistakes can cost time, leverage, or flexibility.”
VA financing can be one of the strongest paths to homeownership for eligible military and veteran buyers in Houston, Katy, Cypress, Sugar Land, Richmond, Fulshear, and nearby communities. But the loan itself does not remove the need for planning. Many of the biggest problems happen when buyers assume the VA process is automatic, simple, or identical to every other loan type.
Why VA loan mistakes matter
A VA loan can offer meaningful advantages for eligible buyers, but those advantages only help when the transaction is handled well from the start. A preventable mistake can slow down underwriting, weaken your offer strategy, create confusion about eligibility, or leave you with unexpected costs after closing. In a large and varied market like Houston, where buyers may be comparing resale homes, new construction, and suburban communities with different timelines, preparation matters.
Mistake #1: Skipping an independent home inspection
One of the most common mistakes is assuming the home does not need a full inspection because the buyer is using a VA loan. That is not a safe assumption. A home can meet minimum property standards and still have repair issues, deferred maintenance, or systems nearing the end of their useful life.
An independent inspection helps you understand the actual condition of the property before closing. That matters whether you are buying an older home in an established Houston neighborhood or a newer property in a growing suburb.
How to avoid it: Schedule a licensed independent inspector as early as your contract timeline allows. Review the report carefully and discuss repair requests, credits, or next steps with your real estate agent and lender as needed.
Mistake #2: Confusing the VA appraisal with a home inspection
A VA appraisal is not the same thing as a home inspection. The appraisal is primarily used to assess value and confirm that the property meets basic VA property requirements. It is not a substitute for a detailed inspection of the roof, HVAC, plumbing, electrical systems, appliances, drainage, or workmanship.
Buyers who confuse the two may move forward without fully understanding the home they are purchasing.
How to avoid it: Treat the appraisal and inspection as two separate steps with two separate purposes. The appraisal supports the loan. The inspection protects your decision-making.
Mistake #3: Misunderstanding VA entitlement and reuse
Another major issue is not understanding how VA entitlement works. Some buyers assume they can only use a VA loan once. Others assume they automatically have full entitlement available no matter what they currently own or financed in the past. Neither assumption is always correct.
Your available entitlement can affect whether you can use a VA loan again, how much remaining entitlement you may have, and what options may exist if you still own a home financed with a VA loan. This becomes especially important for military families dealing with PCS moves, relocations, or a decision to keep a previous home as a rental.
How to avoid it: Ask a VA-approved lender early to review your certificate of eligibility, current loan history, and possible entitlement restoration or reuse scenarios before you start writing offers.
Mistake #4: Waiting too long to involve a VA-approved lender
Some buyers start touring homes before they have spoken with a lender who regularly handles VA financing. That can create avoidable delays later, especially if questions come up about eligibility, documentation, occupancy, or entitlement.
Early lender involvement helps you understand your budget, required paperwork, and likely timeline before you get emotionally attached to a property. It also helps you write cleaner offers with fewer surprises.
How to avoid it: Talk with a VA-approved lender before active home shopping begins. Ask what documents you should gather, what timeline to expect, and whether there are any entitlement or occupancy questions to resolve upfront.
Mistake #5: Overlooking occupancy requirements
VA loans are intended for primary residences, not purely investment purchases. Buyers sometimes assume they can use a VA loan for any property type or occupancy plan without issue. That can create problems if the intended use does not align with VA or lender requirements.
Occupancy questions can also come up when a buyer is relocating to the Houston area, buying ahead of a move, or coordinating around military orders.
How to avoid it: Confirm occupancy expectations with your lender before going under contract. If your move involves military timing, deployment, or a PCS-related exception, ask how that affects documentation and timing.
Mistake #6: Assuming every seller or builder understands VA financing
Not every listing agent, seller, or builder sales representative understands how VA financing works. Some may have outdated assumptions about appraisals, repairs, timelines, or buyer strength. If those misunderstandings are not addressed early, they can affect negotiations and expectations.
This can be especially relevant when comparing resale homes with new construction communities around Houston and its surrounding suburbs.
How to avoid it: Work with professionals who can explain the VA process clearly and proactively. A well-prepared offer, strong communication, and realistic timelines can help reduce confusion on the other side of the transaction.
Mistake #7: Failing to budget for closing and move-in costs
Some buyers focus so heavily on the loan structure that they forget to plan for the rest of the transaction. Even when a VA loan reduces certain upfront barriers, buyers may still face closing costs, prepaid items, inspections, moving expenses, utility setup, repairs, furnishings, and immediate maintenance needs.
How to avoid it: Build a full purchase budget, not just a loan budget. Ask your lender and agent to help you identify likely categories of expense early so you can plan with more confidence.
Mistake #8: Not reviewing timelines and documentation early
VA transactions can move smoothly, but they still require coordination. Delays often happen when buyers wait too long to gather documents, respond to lender requests, schedule inspections, or understand contract deadlines.
That can create unnecessary stress, especially if you are balancing work, family logistics, or a military relocation timeline.
How to avoid it: Review the contract timeline as soon as you go under contract. Keep a checklist of lender documents, inspection dates, appraisal milestones, and contingency deadlines.
Practical prevention steps for Houston-area VA buyers
- Speak with a VA-approved lender before touring homes seriously.
- Confirm your eligibility and discuss entitlement reuse early.
- Budget for inspections, closing costs, and move-in expenses.
- Schedule an independent inspection, even on homes that appear move-in ready.
- Understand that the VA appraisal does not replace an inspection.
- Review occupancy expectations before making an offer.
- Ask questions early if you are buying during a PCS or relocation timeline.
- Keep documents organized so lender requests do not slow you down.
VA loan mistake prevention checklist
- Choose a VA-approved lender early in the process.
- Request a review of your eligibility and entitlement status.
- Clarify whether you have used a VA loan before and what that means now.
- Set a realistic total budget, including non-loan costs.
- Use an independent home inspector.
- Track contract deadlines, inspection periods, and lender conditions.
- Confirm occupancy plans and timing.
- Prepare for extra communication if the seller or builder is unfamiliar with VA financing.
FAQ: VA loan mistakes Houston buyers should avoid
Do I still need a home inspection with a VA loan?
Yes. A VA appraisal does not replace an independent home inspection.
Can I use a VA loan more than once?
In many cases, yes, but it depends on your entitlement, prior VA loan use, and current ownership situation.
Should I talk to a lender before looking at homes?
Yes. Early lender guidance can help you understand budget, eligibility, documentation, and timing before you make an offer.
Can I use a VA loan for an investment property?
VA loans are generally intended for primary residences, so occupancy rules matter.
Do sellers always understand VA financing?
No. Some do, and some do not. Clear communication and strong preparation can help avoid confusion.
What costs should I plan for besides the loan itself?
Plan for inspections, closing costs, prepaid items, moving expenses, utility setup, and possible repairs or immediate home needs.
Final thoughts
VA financing can be a powerful tool for eligible buyers in Houston and surrounding communities, but the best results usually come from preparation, not assumptions. When you understand entitlement, involve the right lender early, schedule inspections, and stay ahead of documentation and deadlines, you give yourself more control and fewer surprises.
Eligibility, entitlement, occupancy, and lender requirements should be confirmed directly with the VA and a VA-approved lender, along with any contract-specific guidance from qualified real estate and legal professionals.
Get a free home valuation here
Visit our website here
Go to our YouTube Channel Here
Call or Contact us:
832-905-9501
mflores@vantagerec.com
Vantage Real Estate Group Powered by PLACE
Michael Flores
Owner/Lead Agent | Vantage Real Estate Group | Keller Williams Signature Realty
or another way