
Categories
VA Loan, Military & Veteran Real Estate, Purchasing Real Estate, Relocation, Home Buying ProcessPublished August 19, 2026
VA Loan Myths That Keep Veterans From Buying a Home
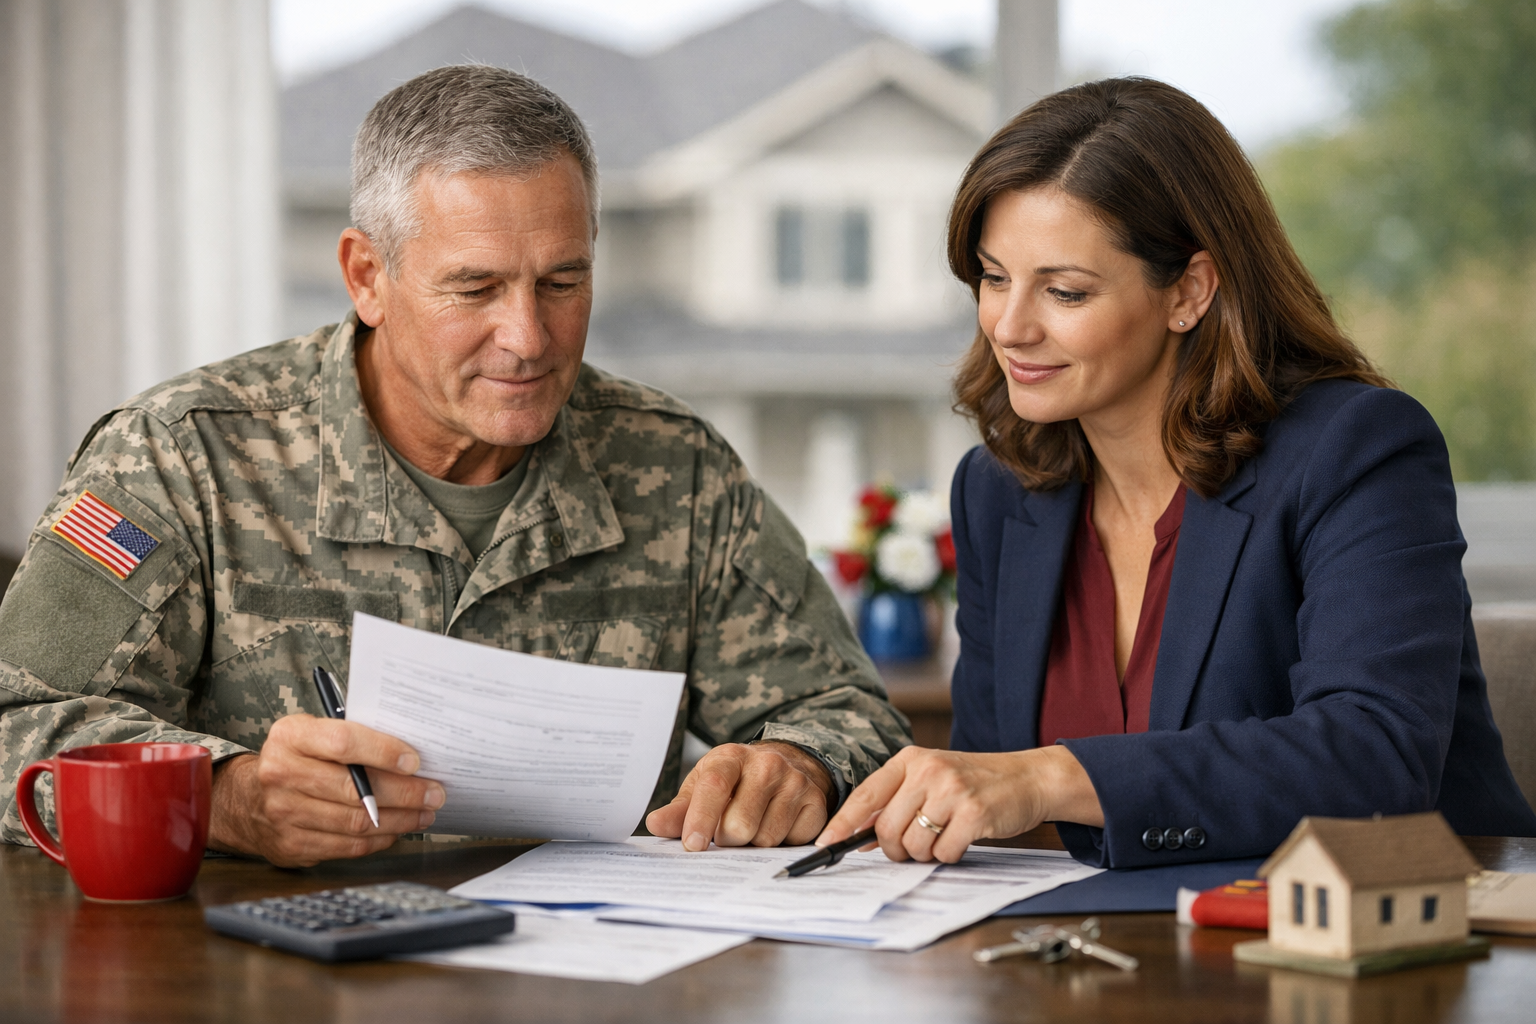
Many veterans, active-duty service members, and eligible surviving spouses put off buying a home because they have heard incomplete or outdated information about VA loans. The VA home loan benefit can be a valuable path to homeownership for qualified buyers, but it has eligibility, lender, occupancy, and property requirements that should be understood before making an offer.
What VA loan myths keep veterans from buying a home?
Common VA loan myths include that you need perfect credit, must make a 20% down payment, can only use the benefit once, cannot compete with conventional buyers, or will have no cash costs at closing. The truth is more nuanced. Eligibility, income, debt, credit profile, entitlement, lender guidelines, property condition, and contract terms all affect a buyer’s options.
Myth 1: You need perfect credit to qualify for a VA loan
Reality: The Department of Veterans Affairs does not publish one universal minimum credit score for every VA borrower. Individual lenders set their own credit and underwriting standards. Credit history matters, but buyers do not necessarily need perfect credit to explore VA financing.
If your credit needs improvement, a VA-approved lender can explain which factors are affecting your application and what steps may help. Before applying, avoid unnecessary new credit accounts, large unexplained deposits, or major financial changes that could complicate underwriting.
Myth 2: VA loans require a 20% down payment
Reality: Eligible buyers may be able to purchase with no down payment, depending on entitlement, loan amount, lender approval, property value, and other factors. A low or zero down payment does not mean buying requires no savings.
Buyers may still need funds for earnest money, inspections, appraisal-related expenses, closing costs, prepaid items, moving, immediate repairs, and emergency reserves. Ask your lender for a complete estimate of your expected cash to close before you begin touring homes.
Myth 3: VA loans have no closing costs
Reality: VA loans can involve closing costs and prepaid expenses. Depending on the transaction and applicable rules, some costs may be paid by the buyer, seller, lender, or another party. Seller concessions can be negotiated, but they are not guaranteed.
Review a loan estimate with your lender so you understand both your estimated monthly payment and the funds you may need before closing.
Myth 4: You can only use your VA loan benefit once
Reality: Many eligible borrowers can use their VA home loan benefit more than once. Whether you have remaining entitlement, can restore entitlement, or can use the benefit while retaining another VA-financed property depends on your individual circumstances.
Do not assume that a prior VA loan prevents you from using the benefit again. Ask a VA-approved lender to review your Certificate of Eligibility and explain your current options.
Myth 5: VA buyers cannot compete with conventional buyers
Reality: A well-prepared VA buyer can present a strong offer. Preapproval, clear lender communication, realistic timelines, thoughtful offer terms, adequate earnest money, and a lender experienced with VA financing can all improve an offer’s competitiveness.
Sellers evaluate the complete offer, including price, financing strength, contingencies, concessions, closing date, and appraisal risk. VA financing does not automatically make an offer weak.
Myth 6: Sellers cannot accept VA loan offers
Reality: Sellers can accept VA-financed offers. A seller may compare offers based on their overall terms, but VA financing itself does not prevent a transaction from closing. Buyers can build confidence by working with professionals who understand the VA process and communicate expectations clearly.
Myth 7: A VA appraisal is the same as a home inspection
Reality: A VA appraisal is not a substitute for a home inspection. The appraisal helps establish value for the lender and includes a review of certain property-condition requirements. A home inspection is a separate, buyer-focused evaluation of the home’s visible condition and systems.
Buyers should strongly consider a general home inspection and any appropriate specialty inspections, such as roof, foundation, pool, sewer, HVAC, pest, or drainage evaluations. In Houston, property-specific concerns may include roof age, drainage, flood history, foundation movement, prior water intrusion, and insurance availability.
Myth 8: VA loans always take longer to close
Reality: Closing time depends on lender capacity, documentation, appraisal scheduling, title work, inspections, repairs, underwriting, and the complexity of the transaction. A VA loan does not automatically mean a slow closing.
Delays can happen with any loan type when documents are incomplete, appraisal issues arise, repairs are needed, or title matters must be resolved. Choose a lender who regularly handles VA loans, submit requested documents promptly, and address concerns early.
Myth 9: You cannot buy a condo or new construction home with a VA loan
Reality: Eligible buyers may be able to use VA financing for certain condos and new-construction homes, but additional requirements can apply. A condominium project may need to meet VA approval requirements. With new construction, the builder, property, appraisal, warranties, completion timeline, and lender requirements can affect eligibility.
Before becoming committed to a specific property, ask your lender whether it is likely to work with VA financing.
Myth 10: VA loans are only for first-time homebuyers
Reality: VA loans are not limited to first-time buyers. Eligible borrowers may use the benefit for a qualifying primary residence even if they have owned a home before. Occupancy requirements apply, so discuss your intended use of the property with a VA-approved lender.
Myth 11: You can use a VA loan for any investment property or vacation home
Reality: VA purchase loans are generally intended for a primary residence and include occupancy requirements. They are not designed for a buyer to purchase a vacation home or a purely investment property. There can be circumstances involving future rental use after the buyer has occupied the home, but buyers should get lender guidance before relying on that strategy.
Myth 12: Every VA borrower pays the VA funding fee
Reality: Some borrowers may be exempt from the VA funding fee, while others may pay a fee that varies based on factors such as loan type, down payment, and prior use of the benefit. In many cases, the funding fee may be financed into the loan. Confirm your status and estimated fee with your lender.
What Houston veterans should consider before using a VA loan
Houston-area buyers should evaluate the full cost and condition of a specific property, not only the loan program. Before making an offer, review estimated property taxes, homeowners insurance, HOA dues, MUD taxes, PID assessments, flood-related information, commute needs, and inspection findings.
It is also wise to ask about roof age, prior insurance claims, drainage, foundation repairs, pool condition when applicable, and known water intrusion. These factors can affect affordability, insurability, negotiations, and long-term ownership costs.
How to prepare for a VA home purchase
- Confirm eligibility and request your Certificate of Eligibility.
- Speak with a VA-approved lender about credit, income, debt, entitlement, and estimated payment.
- Set a comfortable budget that includes taxes, insurance, HOA dues, and maintenance.
- Save for inspections, earnest money, moving, immediate repairs, and reserves, even if you may qualify for low or no down payment.
- Get preapproved before touring homes or making offers.
- Work with a real estate professional and lender who understand VA financing.
- Order a home inspection and any needed specialty inspections during your option period.
- Review insurance availability and cost before removing key contract protections.
Frequently asked questions about VA loan myths
Can I get a VA loan with bad credit?
VA does not publish one universal minimum credit score for all borrowers, but lenders set their own credit standards. If your credit is less than ideal, speak with a VA-approved lender to understand your options and the steps that may improve your eligibility.
Do VA loans require a down payment?
Eligible buyers may be able to purchase with no down payment, depending on entitlement, loan amount, lender approval, property value, and other factors. Buyers should still plan for closing costs, prepaid expenses, inspections, moving, and reserves.
Can I use my VA loan benefit more than once?
Many eligible borrowers can use their VA benefit more than once. Your available entitlement and ability to restore entitlement depend on your prior loans and current circumstances. A lender can review your Certificate of Eligibility and explain your options.
Is a VA appraisal the same as an inspection?
No. A VA appraisal is not a home inspection. Buyers should obtain an independent home inspection to better understand the property’s condition, systems, maintenance needs, and potential repair costs.
Can a seller reject a VA loan offer?
A seller can choose among offers based on the overall terms, but sellers can accept VA-financed offers. Strong preapproval, clear timelines, and well-structured terms can help a VA buyer present a competitive offer.
Can I buy a Houston home with a VA loan?
Eligible buyers can use VA financing to purchase a qualifying primary residence in Houston. Before making an offer, review property taxes, insurance, flood-related information, HOA or district fees, inspections, and the property’s condition with your lender and real estate professional.
Bottom line
VA loan myths should not keep eligible veterans and service members from exploring homeownership. The benefit can offer meaningful advantages, but it works best when you understand the requirements, prepare your finances, and evaluate each property carefully. A VA-approved lender can help you confirm eligibility, entitlement, estimated costs, and loan options that fit your goals.
Watch our Youtube Video
Get a free home valuation here
Visit our website here
Go to our YouTube Channel Here
Call or Contact us:
832-905-9501
mflores@vantagerec.com
Vantage Real Estate Group Powered by PLACE
Michael Flores
Owner/Lead Agent | Vantage Real Estate Group | Keller Williams Signature Realty
or another way